混合云 AI 工作负载编排市场(2026—2031)
混合云 AI 工作负载编排市场规模预计由2026年的75.6亿美元增至2031年的167.2亿美元,预测期复合年增长率为17.21%。北美是当前最大市场,亚太地区增长最快。
市场研究正文
规模、增长、细分、驱动因素与关键问题
当前质量分 100.00,审核状态 accepted。结构化字段已按 RoboInd 内容层级组织。
核心结论
混合云 AI 工作负载编排市场规模预计由2026年的75.6亿美元增至2031年的167.2亿美元,预测期复合年增长率为17.21%。北美是当前最大市场,亚太地区增长最快。
市场走势
结构化指标
| 指标 | 年份 | 数值 | 性质 |
|---|---|---|---|
| 复合年增长率 | 2031 | 17.21% | 机构预测 |
| 市场规模 | 2026 | USD 7.56 billion | 机构预测 |
| 市场规模 | 2031 | USD 16.72 billion | 机构预测 |
细分市场份额
市场结构
| 维度 | 细分项 | 年份 | 份额 |
|---|---|---|---|
| application | GPU scheduling and allocation | 2025 | 33.180% |
| component | software | 2025 | 62.720% |
| deployment_environment | cloud | 2025 | 57.280% |
| end_user | cloud service providers and GPU-as-a-Service providers | 2025 | 31.610% |
| geography | North America | 2025 | 38.920% |
| organization_size | large enterprises | 2025 | 64.370% |
关键结论
- application 维度中,GPU scheduling and allocation 在 2025 年的公开份额为 33.18%。
- component 维度中,software 在 2025 年的公开份额为 62.72%。
- deployment_environment 维度中,cloud 在 2025 年的公开份额为 57.28%。
- end_user 维度中,cloud service providers and GPU-as-a-Service providers 在 2025 年的公开份额为 31.61%。
- geography 维度中,North America 在 2025 年的公开份额为 38.92%。
- organization_size 维度中,large enterprises 在 2025 年的公开份额为 64.37%。
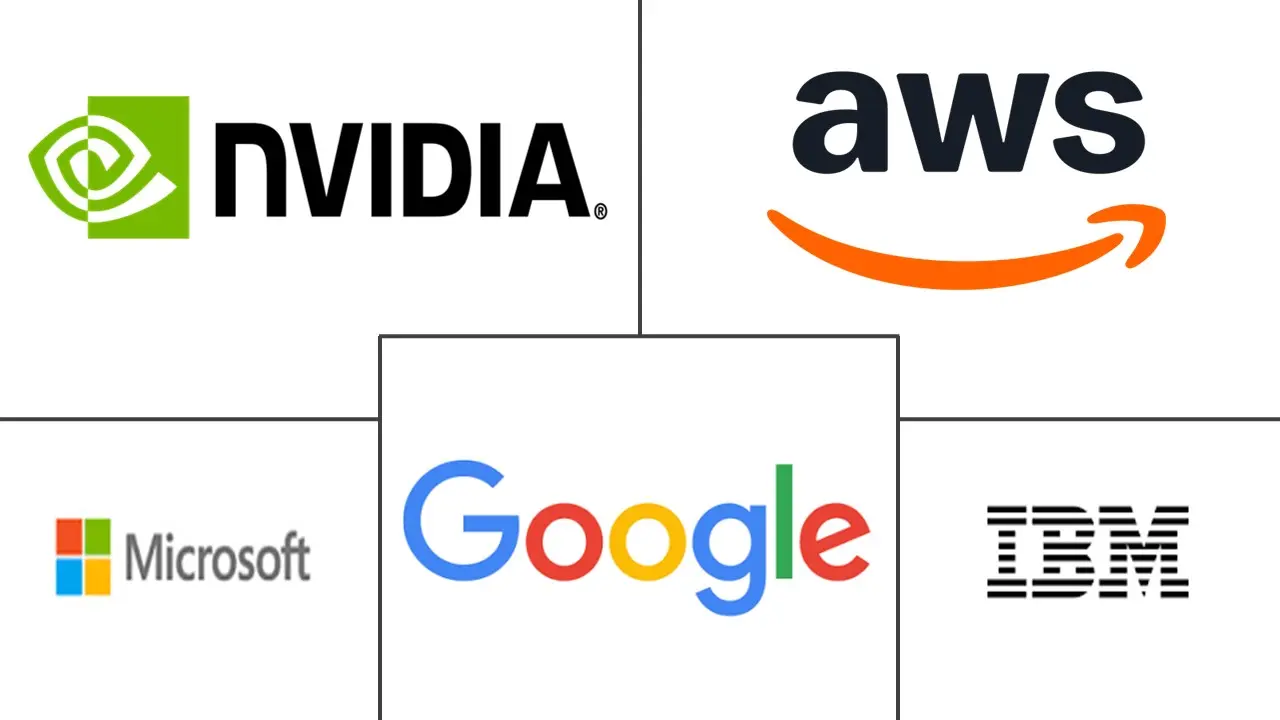
主要参与者
- NVIDIA Corporation
- Amazon Web Services, Inc.
- Microsoft Corporation
- Google LLC
- IBM Corporation
增长驱动因素
| 因素 | 影响 CAGR | 地区相关性 | 影响周期 |
|---|---|---|---|
| Accelerating LLM Training and Inference Deployment | +5.000% | Global | Short term (≤ 2 years) |
| GPU Utilization and Compute Cost Optimization | +3.800% | Global, with highest intensity in North America and Europe | Short term (≤ 2 years) |
| Hybrid Data Residency and Sovereign AI Requirements | +3.200% | Europe, Asia-Pacific core, spill-over to Middle East | Medium term (2-4 years) |
| Distributed AI Scheduling Across Heterogeneous Accelerators | +2.000% | North America and Asia-Pacific core | Medium term (2-4 years) |
| Agentic AIOps and Policy-Driven Automation Adoption | +1.600% | Global, led by North America and Western Europe | Medium term (2-4 years) |
| Energy-Aware Scheduling and Sustainable AI Infrastructure | +0.900% | Europe, North America, Asia-Pacific | Long term (≥ 4 years) |
市场制约因素
| 因素 | 影响 CAGR | 地区相关性 | 影响周期 |
|---|---|---|---|
| Heterogeneous Hardware and Cloud API Interoperability Gaps | -2.400% | Global | Short term (≤ 2 years) |
| Shortage of AI Infrastructure Orchestration Specialists | -1.900% | Global, with acute impact in Asia-Pacific and Middle East and Africa | Medium term (2-4 years) |
| Multi-Tenant GPU Security and Isolation Complexity | -1.300% | North America and Europe | Medium term (2-4 years) |
| Migration Friction Across Hybrid Control Planes | -0.800% | Global | Long term (≥ 4 years) |
报告关注的关键问题
What is the size of the hybrid cloud AI workload orchestration market?
The hybrid cloud AI workload orchestration market size is USD 7.56 billion in 2026 and is forecast to reach USD 16.72 billion by 2031 at a CAGR of 17.21%.
What is driving adoption of hybrid AI workload orchestration?
Large language model workloads, GPU utilization needs, data-residency requirements, and multi-accelerator environments are driving adoption. These requirements make coordinated scheduling, policy enforcement, and workload placement more important when compute resources span cloud and on-premises environments.
Which component holds the largest share?
Software held 62.72% of revenue in 2025 because scheduling, governance, and policy enforcement are central platform functions. These capabilities combine operating controls that enterprises need across shared resources, deployment locations, and workloads with different access and compliance needs. They can also reduce the burden of managing disconnected scheduling, governance, and reporting processes when AI teams use more than 1 infrastructure environment.
Which deployment environment is expanding fastest?
On-premise deployments are projected to expand at a CAGR of 17.59% through 2031 as regulated users require greater control over data and audit records. These deployments can retain sensitive processing within a defined location while allowing organizations to use cloud resources when capacity needs exceed local infrastructure.
Which application is expanding fastest?
Governance, multi-tenancy, and policy enforcement are projected to expand at a CAGR of 18.16% through 2031.
Which region is expanding fastest?
Asia-Pacific is projected to expand at a CAGR of 18.23% through 2031, supported by sovereign AI programs and domestic infrastructure investment. Demand is also linked to national data-residency policies and the need to coordinate domestic infrastructure with commercial cloud capacity.
市场概览
- 增长最快市场:亚太地区
- 最大市场:北美
- 市场集中度:中等
查看来源:Mordor Intelligence